12. Sep 2022
Scope 1, 2, and 3 emissions are the three categories the Greenhouse Gas (GHG) Protocol uses to classify a company's carbon footprint. Scope 1 covers direct emissions from sources a company owns or controls, such as a fleet's own vehicles. Scope 2 covers indirect emissions from purchased energy, such as electricity. Scope 3 covers every other indirect emission in the value chain – which, for most transport and logistics buyers, is where fuel production and outsourced transport emissions land (GHG Protocol Corporate Standard, retrieved 2026-08-28).
For a fleet operator, that framework is no longer an academic accounting exercise. It is the language that CSRD reporting, SBTi target-setting, and fuel-supplier documentation all speak. A fleet that cannot translate its own fuel purchasing into Scope 1, 2, and 3 terms will struggle to satisfy any of the three. This guide brings four threads that fleet buyers currently have to piece together from separate articles – the Scope 1/2/3 framework itself, CSRD's double materiality requirement, the Science Based Targets initiative (SBTi), and Proof of Sustainability (PoS) documentation – into one practical guide, then closes with a reporting workflow that ties them together.
Key Takeaways
- Scope 1 = direct emissions from owned/controlled sources (a fleet's own vehicles). Scope 2 = indirect emissions from purchased energy. Scope 3 = everything else in the value chain, including upstream fuel production and outsourced transport – the category where most fleet fuel-purchasing decisions actually register.
- Biofuel Express customers achieved 548,000 tonnes of CO2 reduced in 2025, an 86% average reduction against regular diesel – equivalent to roughly 18,700 trips around the Earth, or the annual emissions of about 116,000 people (Biofuel Express, Group Sustainability Report 2025).
- CSRD changed substantially in 2026: the Omnibus I Directive raised the mandatory-reporting threshold to more than 1,000 employees and over €450 million net turnover, and pushed the next reporting wave's start back to financial year 2027 (Council of the EU, 24 February 2026).
- Fuel switching to HVO100 or B100 is one of the fastest, most measurable levers a fleet has for both Scope 1 reduction and progress towards an SBTi target, because it changes reported emissions without waiting for a vehicle-replacement cycle.
- A valid Proof of Sustainability (PoS) document is the paper trail that makes a renewable-fuel emissions claim auditable; a fleet that cannot verify its PoS documents cannot defend its emissions numbers if a report is ever questioned.
Scope 1, 2 & 3 emissions are the GHG Protocol Corporate Standard's three-part classification for a company's carbon footprint, and together they are the vocabulary that virtually every corporate emissions report, climate target, and regulatory disclosure is now built on (GHG Protocol Corporate Standard, retrieved 2026-08-28).
Scope 1 – Direct emissions. Emissions from sources a company owns or controls: fuel combusted in a fleet's own trucks, vans, or machinery, or gas burned in an owned facility. If your company holds the fuel card and the vehicle title, the tailpipe emissions are yours to report here.
Scope 2 – Indirect emissions from purchased energy. Emissions from the electricity, steam, heat, or cooling a company buys, even though the generation happens elsewhere. For a fleet operator, this typically means grid electricity used at depots, warehouses, or – increasingly – EV charging infrastructure.
Scope 3 – Everything else in the value chain. All other indirect emissions a company is responsible for but does not directly control, split across 15 categories under the GHG Protocol's Scope 3 standard. For a transport or logistics buyer, two category groups matter most. Category 3 covers fuel- and energy-related activities not already counted in Scope 1 or 2 – broadly, the upstream, well-to-tank emissions embedded in producing the fuel a fleet burns. Categories 4 and 9 cover upstream and downstream transportation and distribution, meaning any freight moved by subcontracted hauliers rather than a fleet's own vehicles.
One nuance matters specifically for fuel-purchasing decisions: under common GHG accounting convention, the biogenic CO2 released when combusting a renewable fuel such as HVO100 or B100 is reported separately from a company's Scope 1 total, rather than added to it (the smaller quantities of N2O and methane from combustion still count). That convention is a direct part of why switching a fleet's own vehicles to a renewable fuel visibly lowers reported Scope 1 fossil-CO2 figures, independent of any Scope 3 upstream accounting.
A common misconception is that Scope 3 is optional because the GHG Protocol itself does not mandate it for all reporters. In practice, once a company is in scope for CSRD or has set a target through SBTi, Scope 3 disclosure becomes a binding requirement rather than a voluntary extra – covered in detail in the sections below.
The Scope 1/2/3 framework matters to a fleet's fuel purchasing for one direct reason: it is the structure that determines which emissions a fuel-switching decision actually moves, and by how much. A fleet operator who understands where a litre of diesel or HVO100 registers – Scope 1 combustion, Scope 3 upstream production, or both – can make a fuel decision that is defensible in a report, not just intuitively sustainable.
The scale of what is achievable here is not theoretical. Biofuel Express's own customers achieved 548,000 tonnes of CO2 reduced in 2025, an 86% average reduction against regular diesel across the volumes supplied – equivalent to roughly 18,700 trips around the Earth, or the annual emissions of about 116,000 people (Biofuel Express, Group Sustainability Report 2025). That is aggregate customer data, not a single case study, and it illustrates the order of magnitude a fuel-purchasing decision can reach once it is tracked and reported properly – the exact task this guide is about.
With the Biofuel Express Insight-portal Biofuel Express has stepped up their game. I wish that other suppliers would also be able to provide such quality of data. The portal has become an essential tool for our group, and it is widely used across various functions and geographical areas - from purchasing, to business controllers, fuel managers, and of course - the sustainability department.’’- Biofuel Express customer
Fuel purchasing decisions rarely stay inside a single scope. Switching a fleet's own vehicles from fossil diesel to HVO100 lowers reported Scope 1 fossil-CO2 directly (per the biogenic-CO2 convention above), while a supplier's own upstream production emissions – which show up in a fleet buyer's Scope 3 Category 3 – depend on the feedstock and production pathway the supplier used, which is exactly what a valid Proof of Sustainability document is meant to prove. Understanding which scope a purchasing decision affects is the first input into the two reporting frameworks covered next: CSRD and SBTi.
Double materiality is the requirement, introduced by the EU's Corporate Sustainability Reporting Directive (CSRD), that an in-scope company report a sustainability matter if it is material from either of two directions: impact materiality (how the company's own operations affect people and the environment – an "inside-out" view) or financial materiality (how sustainability risks and opportunities affect the company's own financial performance – an "outside-in" view). A matter is reportable if it clears either threshold; it does not need to clear both at once.
For a fleet operator, fuel-related emissions data is close to the clearest possible example of a double-material topic. It is almost always impact-material, since fuel combustion is a direct, measurable environmental effect. It is increasingly financially material too, as carbon pricing under EU ETS2, tightening HDV CO2 standards, and shifting customer procurement criteria turn fuel choice into a cost and revenue-risk factor that shows up on the balance sheet, not just the sustainability page. (For the fuller regulatory picture behind that financial-materiality case, see Biofuel Express's guide to EU climate regulations for transport.)
CSRD's applicability has changed substantially since the directive first entered into force, and most content written about it before 2026 is now out of date on this specific point. Two changes happened in sequence. First, a 2025 "Stop the Clock" Directive delayed the reporting start date for later waves of companies by two years. Then the Omnibus I Directive raised the thresholds themselves: approved by the Council of the EU on 24 February 2026, published in the Official Journal as Directive (EU) 2026/470, and in force from 18 March 2026 (Council of the EU, press release, 24 February 2026; DLA Piper GENIE, "CSRD: Amendments under Omnibus I finalised", 2026).
Two things make CSRD relevant to fleets well below the 1,000-employee threshold. First, being outside CSRD's mandatory scope does not remove commercial pressure: a fleet's own customers who are in scope will increasingly ask their suppliers – including hauliers and fuel-dependent contractors – for emissions data to complete their own Scope 3 disclosures, since a reporting company's own upstream transportation emissions (GHG Protocol Category 4) depend on data from exactly this kind of supplier. Second, "not yet in scope" and "will never need this data" are different things; a fleet that starts tracking fuel-related Scope 1 and Scope 3 data now, using a system such as Biofuel Express Insight for real-time CO2e tracking, is not rebuilding a reporting function from scratch the day a customer or a threshold change brings it into scope. For the fuller mechanics of how double materiality assessments work in practice, see Biofuel Express's dedicated guide, How CSRD's Double Materiality Requirement Affects All Companies, Large and Small.
The Science Based Targets initiative (SBTi) is the organisation that validates corporate emissions-reduction targets against the trajectory climate science says is needed to limit warming, giving companies an externally verified benchmark rather than a self-declared one. As of 22 January 2026, 10,000 companies worldwide have SBTi-validated targets, representing more than 40% of global market capitalisation – up from the first company validated in 2015 and the 1,000th in 2021, with more than 2,800 new validations added in 2025 alone (Science Based Targets initiative, 22 January 2026).
Companies pursue SBTi validation for reasons that are only partly altruistic. Investors and lenders increasingly treat a validated target as a proxy for credible climate governance. Large customers now routinely ask suppliers whether they have one as part of procurement due diligence. And getting ahead of regulatory direction – ETS2's carbon pricing, tightening HDV CO2 standards – is cheaper than reacting to it later. SBTi's Corporate Net-Zero Standard also requires a company to set a Scope 3 target once Scope 3 emissions reach 40% or more of its total footprint (SBTi Corporate Net-Zero Standard, v1.3.1, April 2026) – a threshold that nearly every transport-reliant or fuel-dependent business crosses, since purchased fuel and outsourced transport typically dwarf a company's direct operational emissions. SBTi has a Version 2.0 update to this standard in development, which is expected to move away from a single percentage threshold towards requiring targets on material Scope 3 categories specifically; fleet operators tracking Scope 3 data under the current rule are well positioned for that shift regardless of its final form.
Fuel switching is one of the fastest, most measurable levers a fleet has towards an SBTi target, precisely because it changes reported emissions on the fuel volumes already being purchased, without waiting for a vehicle-replacement cycle. As established in Biofuel Express's own guides, HVO100 delivers up to a 90% CO2 reduction against fossil diesel, and B100/RME biodiesel delivers up to a 70% CO2 reduction – figures that translate directly into Scope 1 progress against a near-term target once the fuel is in the tank.
Biofuel Express applies this same reasoning to its own operations, not only to customer fuel supply. The company has held its own SBTi commitment since 2022, with targets formally approved in March 2023, and holds ISO 9001:2015 (quality management) and ISO 14001:2015 (environmental management) certification, recertified in 2024 and valid to 2027 (Biofuel Express, certifications page, retrieved 2026-08-28). Those credentials are cited here as an example of practising what this guide teaches – tracking, validating, and holding an emissions target to the same external standard being described – not as a sales claim. For the fuller mechanics of how SBTi target-setting works, including near-term versus net-zero targets and the validation process, see Sustainable Growth: A Deep Dive into the Science Based Targets Initiative.
A Proof of Sustainability (PoS) is the documentary evidence, issued under certification schemes such as ISCC or REDcert, that a specific batch of renewable fuel meets the sustainability and GHG-emissions-savings criteria set out in the EU's Renewable Energy Directive. In practical terms, it is the document that turns a supplier's "this fuel cuts your emissions by X%" claim from a marketing statement into an auditable fact.
A PoS is not a general certificate covering a supplier's whole operation; it is issued per consignment, tracked through a mass-balance chain-of-custody system that allows sustainable and conventional feedstocks to be mixed in the same physical supply chain while keeping their sustainability characteristics separately accounted for. Under EU Implementing Regulation (EU) 2022/996, once a consignment's PoS has been used to meet a supplier's obligation, that batch is considered withdrawn from the mass-balance mixture, and no further PoS can be issued against it – the mechanism that is meant to prevent the same litre of fuel being counted as a carbon saving twice.
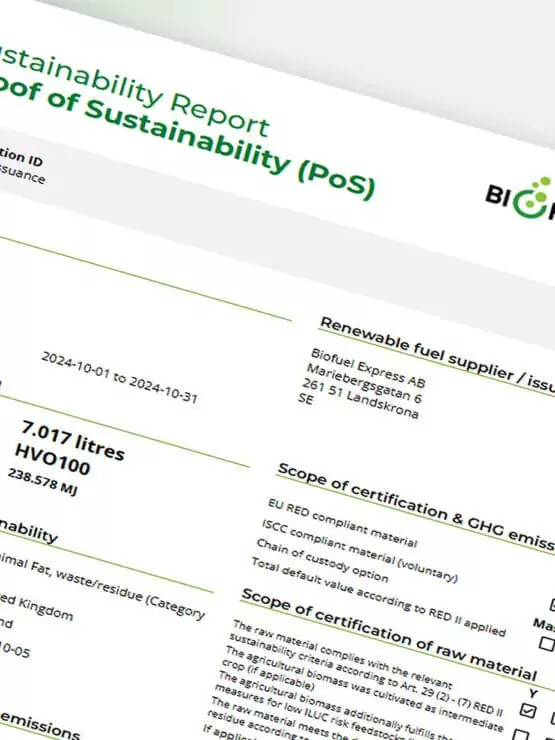
Tracking this at scale – rather than filing PDFs from individual deliveries and hoping they add up at year-end – is exactly the traceability problem Biofuel Express Insight is built to solve; Insight 2.0's traceability features tie delivered volumes to their underlying PoS documentation automatically, rather than leaving that reconciliation to a spreadsheet. For a full walkthrough of what a PoS document is and how it fits into RED compliance, see What Is Proof of Sustainability (PoS)? For a practical checklist on verifying the ones you already receive, see Are You Really Receiving a Valid Proof of Sustainability (PoS)?
A defensible emissions report is not produced in the week before a deadline; it is the output of a small number of things tracked consistently across the year. The workflow below brings the four threads above together into what a fleet operator should actually be doing, month by month and year by year.
| Cadence | What to track | Which thread it feeds |
|---|---|---|
| Every delivery | Collect the Proof of Sustainability for every renewable-fuel delivery; check it against the red-flag list above before filing it | Scope 1/3 evidence base |
| Monthly | Log fuel volumes by depot and vehicle class, split by fossil and renewable fuel; log purchased electricity for depots and any EV charging | Scope 1 and Scope 2 raw data |
| Quarterly | Reconcile logged volumes against supplier invoices and PoS documents; flag any gaps or mismatches while they are still easy to trace | PoS integrity |
| Quarterly | Review outsourced or subcontracted transport volumes and, where available, request emissions data from hauliers | Scope 3, Categories 4 and 9 |
| Annually | Compile the full GHG inventory: Scope 1 direct combustion, Scope 2 purchased energy, Scope 3 fuel- and transport-related categories | Full Scope 1/2/3 inventory |
| Annually | If in scope for CSRD, run or refresh the double materiality assessment against the current-year inventory | CSRD readiness |
| Annually | If an SBTi target is in place, benchmark the year's inventory against the target trajectory and document progress | SBTi progress tracking |
The single hardest part of this workflow in practice is not any individual step; it is keeping the four threads reconciled with each other as the year goes on, rather than discovering at report time that the PoS archive, the fuel-volume log, and the emissions inventory tell three slightly different stories. This is the specific gap Biofuel Express Insight is designed to close: real-time CO2e tracking against delivered fuel volumes, tied to the underlying PoS documentation, with downloadable Sustainability Reports that turn the annual compilation step above from a manual reconciliation exercise into an export. A fleet operator who wants to work through this workflow against their own fuel-purchasing timeline can reach Biofuel Express directly via contact. Once your reporting data supports the case for switching, see This Is Why Your Company Needs Renewable Fuels for the ROI and compliance business case.
For a fleet operator already tracking Scope 1, 2, and 3 emissions individually, the more advanced question is how the four threads in this guide reinforce – or complicate – each other, because the interactions are where the real reporting decisions sit.
The clearest interaction is between Scope 3 and CSRD's double materiality requirement. Scope 3 is technically voluntary under the GHG Protocol itself, but once a company is in scope for CSRD, its double materiality assessment will almost always identify fuel- and transport-related Scope 3 categories as material – which converts a voluntary accounting choice into a binding disclosure requirement. A fleet's Scope 3 data readiness should not wait for a CSRD deadline to be built.
A second interaction sits between SBTi and Scope 3: because SBTi's Corporate Net-Zero Standard requires a Scope 3 target once Scope 3 reaches that 40% threshold, and because purchased fuel and outsourced transport routinely exceed it for logistics-reliant companies, an SBTi commitment effectively forces the same Scope 3 data-collection discipline that CSRD's materiality assessment would eventually require anyway. A company building towards either one is, in practice, building towards both.
The third interaction is the one this guide is built around: Proof of Sustainability documents are the evidentiary layer underneath every claim made in the other three threads. A Scope 1 reduction claim from switching to HVO100, a CSRD disclosure describing lower fuel-related emissions, and an SBTi progress report citing the same fuel switch are all, ultimately, only as credible as the PoS trail behind the fuel volumes involved. Treating PoS collection as a compliance afterthought rather than the foundation the other three threads sit on is the most common gap in an otherwise well-intentioned reporting programme.
Scope 1 covers direct emissions from vehicles a fleet owns or controls – the fuel burned in its own trucks. Scope 3 covers indirect emissions elsewhere in the value chain that the fleet does not directly control, including the upstream emissions embedded in producing the fuel it buys (GHG Protocol Category 3) and any freight moved by subcontracted hauliers rather than the fleet's own vehicles (Categories 4 and 9).
Only if your company (or your EU-based operations, for a non-EU group) exceeds the current threshold: more than 1,000 employees and over €450 million net turnover, following the Omnibus I Directive that entered into force on 18 March 2026. Companies already reporting under the pre-Omnibus threshold since financial year 2024 remain in scope; other large undertakings begin reporting from financial year 2027. Many companies below the threshold still face indirect pressure to supply emissions data to in-scope customers completing their own Scope 3 disclosures.
Yes, for the fossil-CO2 portion of the total. Under common GHG accounting convention, the biogenic CO2 released when combusting HVO100 is reported separately from a company's Scope 1 total rather than added to it, so switching a fleet's own vehicles to HVO100 – which delivers up to a 90% CO2 reduction against fossil diesel – lowers reported Scope 1 fossil-CO2 figures directly, without waiting for a vehicle-replacement cycle.
An incomplete or unverifiable PoS means the emissions-savings claim behind that fuel delivery cannot be defended if a report, an auditor, or a customer's due-diligence process ever questions it. In practice, this can mean a Scope 1 or Scope 3 reduction claimed in a report has to be walked back or removed. Checking every PoS against the red-flag list in this guide before filing it is the cheapest way to avoid that outcome.
No – SBTi validation and emissions reporting are separate things. A company can measure and report Scope 1, 2, and 3 emissions without ever submitting a target to SBTi for validation. An SBTi target is a voluntary, externally validated commitment on top of that reporting, and many companies pursue one specifically because investors or large customers increasingly expect it as evidence of credible climate governance.
Annually, at minimum, covering a full financial year of Scope 1, 2, and 3 data – but the workflow behind that annual report works best as a continuous process, not a once-a-year exercise. Reconciling fuel volumes and PoS documents quarterly, as set out in the reporting workflow above, is what makes the annual compilation accurate rather than a rushed, error-prone scramble.
The single most important takeaway from this guide: Scope 1, 2, and 3 emissions are not an abstract accounting exercise for a fleet operator – they are the shared language that CSRD reporting, SBTi target-setting, and fuel-supplier documentation all depend on, and a fleet that can translate its own fuel purchasing into that language is positioned to satisfy all three at once rather than treating them as separate projects.
CSRD's scope and timeline changed materially in 2026 under the Omnibus I Directive, SBTi has now validated 10,000 companies globally, and Proof of Sustainability documentation remains the evidentiary layer that makes every emissions claim in between defensible. None of that changes the practical answer for a fleet operator: track fuel volumes and PoS documents consistently, understand which scope each fuel-purchasing decision affects, and treat the annual report as the output of a year-round workflow rather than a one-off compliance task. Biofuel Express's contact page is the starting point for working through that reporting workflow against your fleet's own fuel-purchasing timeline.
This guide is compiled and maintained by Biofuel Express from the GHG Protocol Corporate and Scope 3 Standards, primary EU legislative sources (via the Council of the EU and EUR-Lex), the Science Based Targets initiative, ISCC and REDcert scheme documentation, and Biofuel Express's own Group Sustainability Report 2025, and it will be revised as CSRD's Omnibus-driven scope, the SBTi validation count, and PoS scheme requirements continue to develop.
Framework and Regulation:
Targets and Documentation:
Fuel-Switching Levers:
Tools and Credentials:
"*" indicates required fields